



Banks
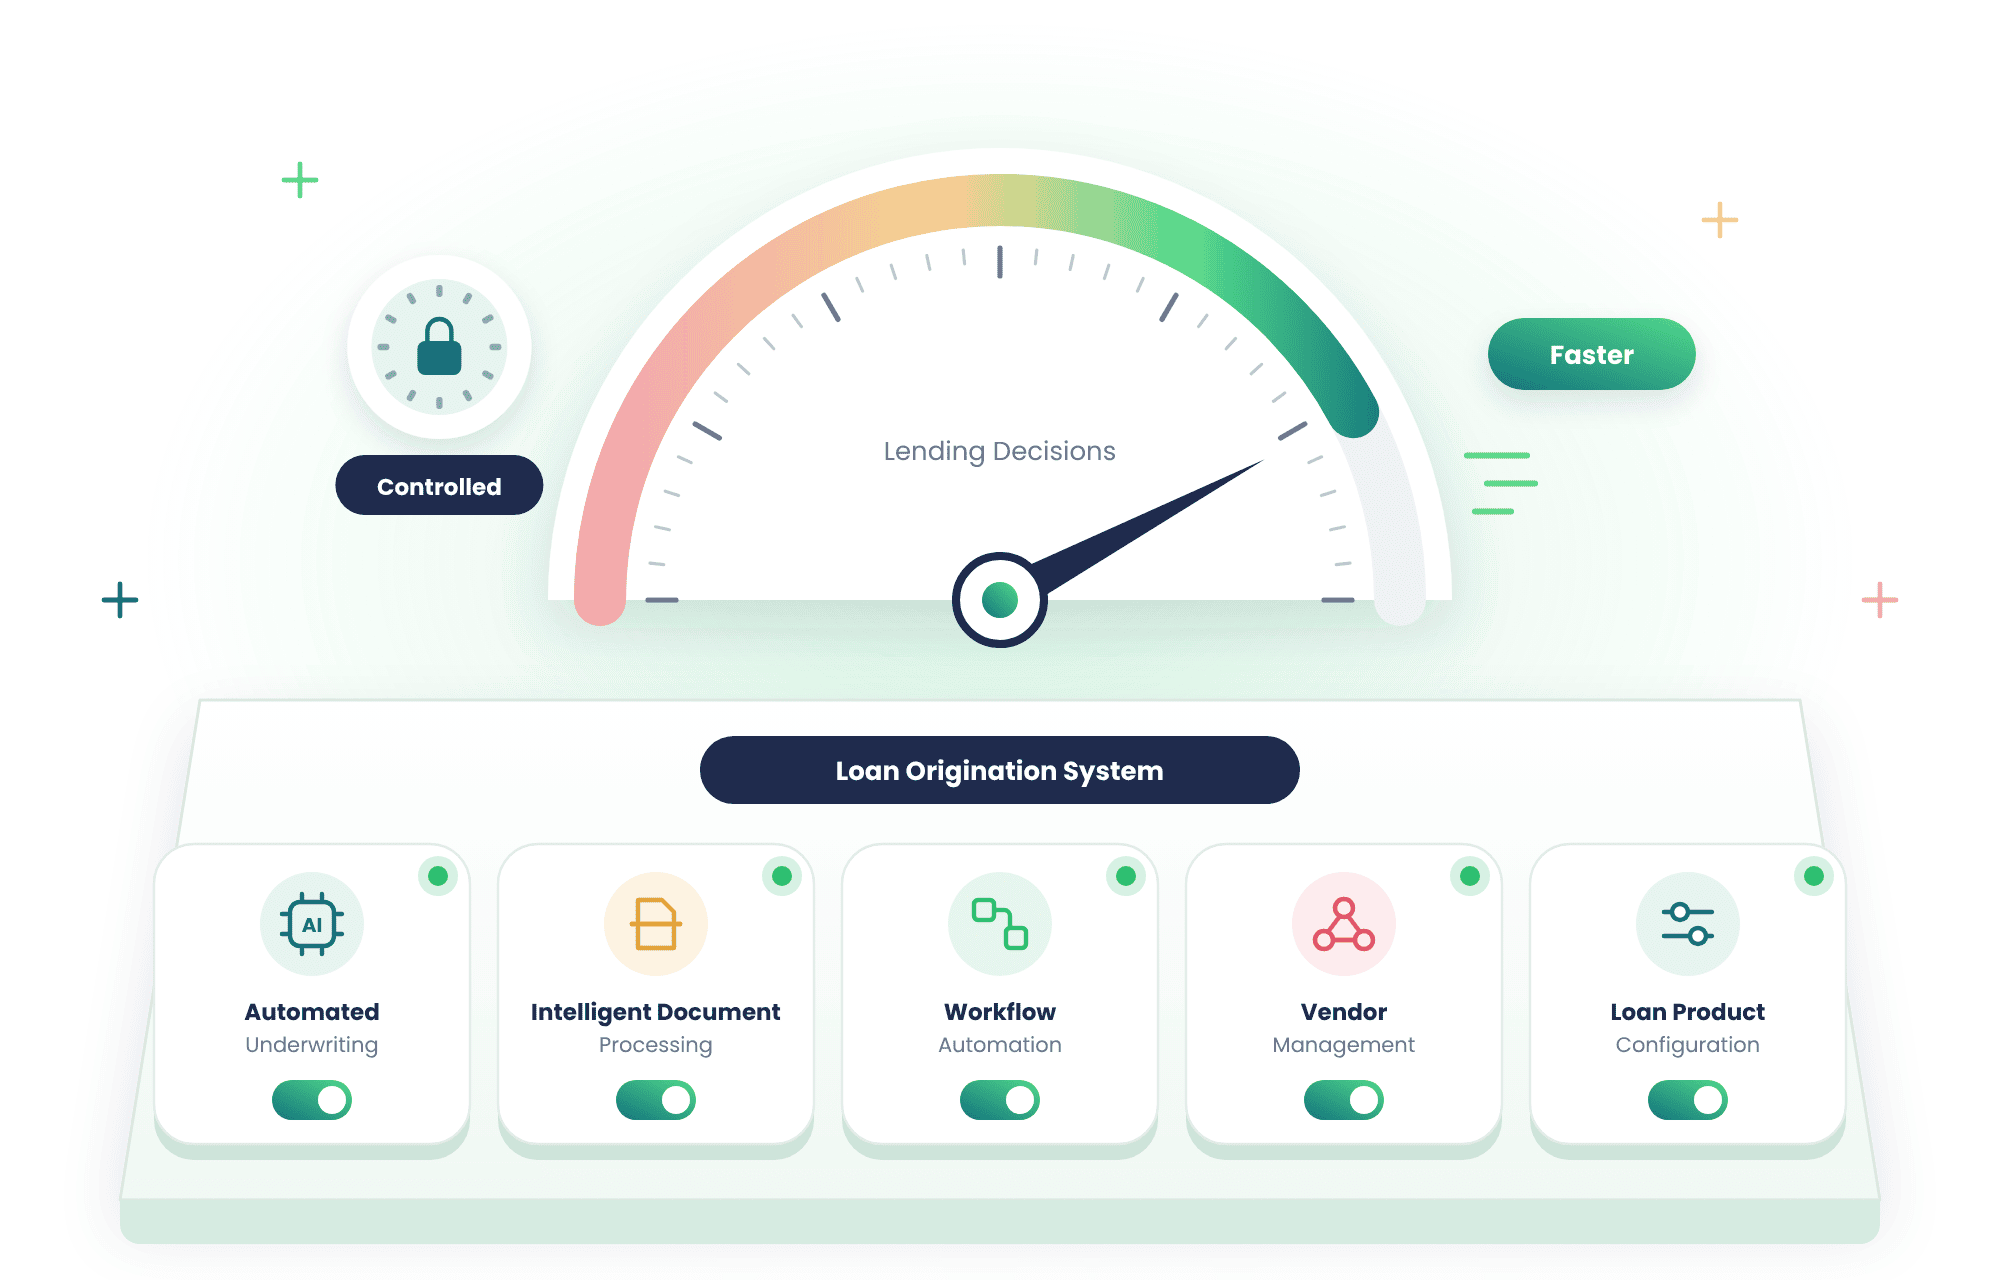
Standardise loan origination workflows across products, teams and channels while improving operational visibility and credit decision consistency.
 AI-Powered Loan Origination System Software
Disconnected systems, manual reviews, and fragmented workflows can slow down the loan application process and make lending operations difficult to scale. Fintly's Loan Origination System (LOS) helps financial institutions digitise and manage the complete origination journey, from lead capture and application intake to underwriting, approval and disbursement.
For Singapore lenders, Fintly LOS supports Singpass Myinfo-first onboarding, credit bureau checks through Credit Bureau Singapore and the Moneylenders Credit Bureau, agentic underwriting with Income, Bureau and Banking Analysis, and Agentic PD for structured borrower discussions.
256+
Customers Worldwide
99.999%
Uptime
Global Presence
Across 40+ Countries
BUILT FOR GOVERNANCE & CONTROL
Managing lending operations requires more than speed. Institutions also need visibility, accountability, and operational control. Fintly LOS includes governance capabilities that help lending teams maintain oversight throughout the origination journey.
Track decisions, approvals, status changes, workflow actions, and user activity through immutable audit records.
Support customer due diligence, verification checkpoints, and controlled approval workflows.
Connect with external verification providers, LMS platforms, core banking systems and third-party services through governed integration workflows.
Manage access across operations, underwriting, risk, compliance, vendor and management teams.
Capture loan applications from branches, digital channels, partner networks, APIs and referral ecosystems through a unified origination platform.
Combine business rules, financial assessment data, risk scoring and approval workflows to support faster and more consistent lending decisions.
Coordinate legal, valuation, verification, and third-party review activities through structured vendor workflows, SLA monitoring, and centralised tracking.
Launch and manage multiple lending products, eligibility criteria, workflows and document requirements without extensive development effort.
AI agents assemble Income, Bureau and Banking Analysis into a draft credit memo with cited evidence, so underwriters review and decide rather than compile. Every recommendation remains subject to human approval.
Configure checks for licensed moneylenders and pawnbrokers, such as mandatory MLCB checks, loan and fee caps, and pledge ticket generation, as governed by rules within the workflow.
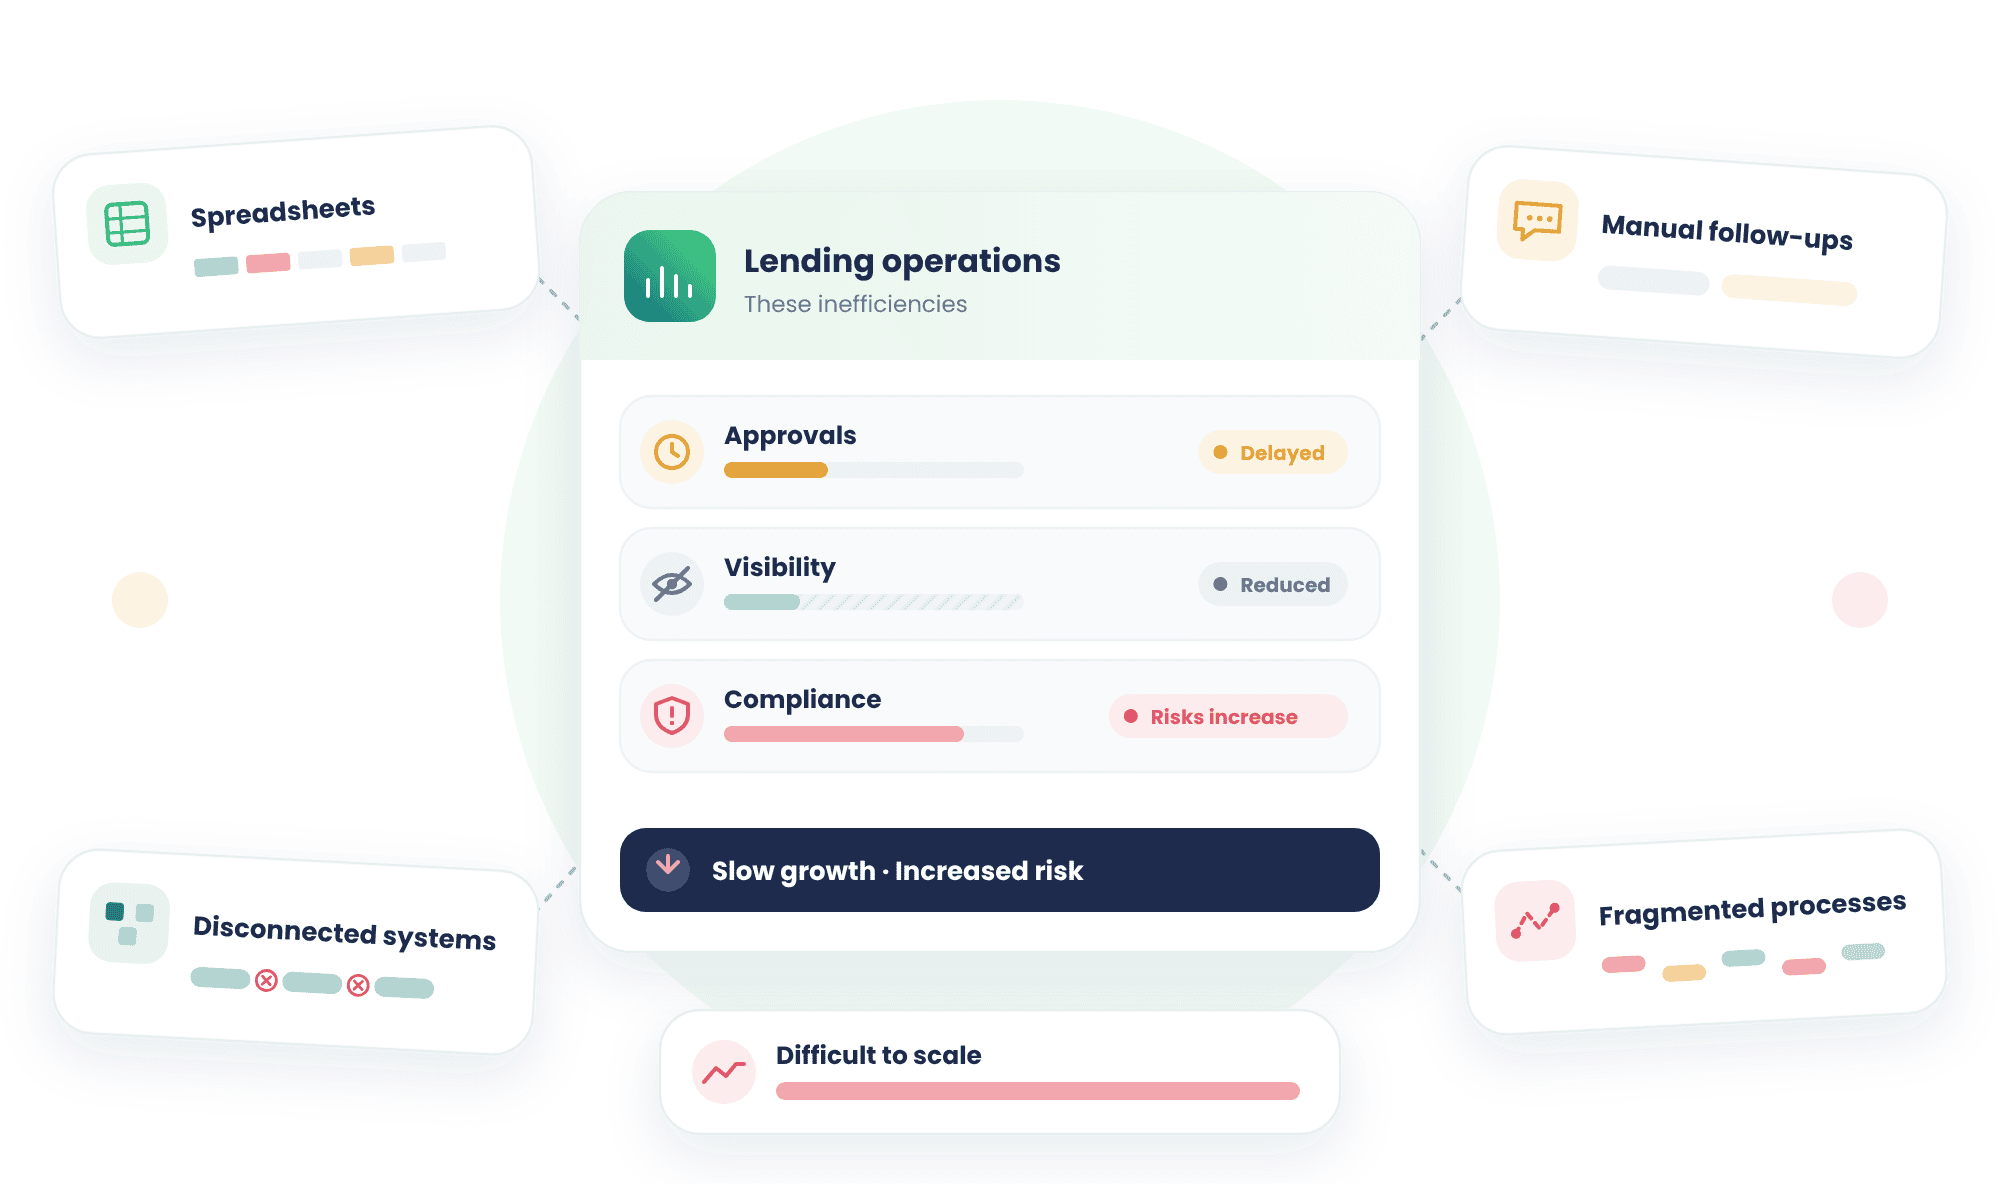
Many lenders continue to manage origination activities through disconnected systems, manual reviews, and spreadsheet-based workflows. These processes increase operational effort, reduce visibility, and create bottlenecks across application processing and underwriting.
As application volumes grow, institutions need greater automation, consistency, and operational control to scale lending efficiently.
Collect applications, perform eligibility checks and route opportunities through configurable intake workflows.
Manage customer onboarding, documentation, verification, and application processing through structured workflows.
Apply business rules, risk assessments and approval frameworks to support faster credit decisions.
Manage pre-disbursement reviews, approval gates, and funding workflows through controlled operational processes.
WHO USES FINTLY LOS
Standardise loan origination workflows across products, teams and channels while improving operational visibility and credit decision consistency.

Reduce processing delays and manage growing application volumes through workflow automation and structured underwriting processes.

Support borrower onboarding, verification, affordability reviews, and loan processing through a controlled digital workflow environment.

Digitise pledge intake, item valuation, pledge ticket issuance and redemption tracking within a controlled, audit-ready workflow.

Launch digital-first lending journeys with automated onboarding, underwriting and approval workflows.

Improve SME lending operations through configurable origination workflows, structured assessments, and automated case management.

Coordinate documentation, verification, underwriting, and approvals through one unified platform.
CONNECTED LENDING ECOSYSTEM
Fintly LOS is designed to operate within existing lending technology environments, helping institutions modernise origination workflows without replacing core operational systems.
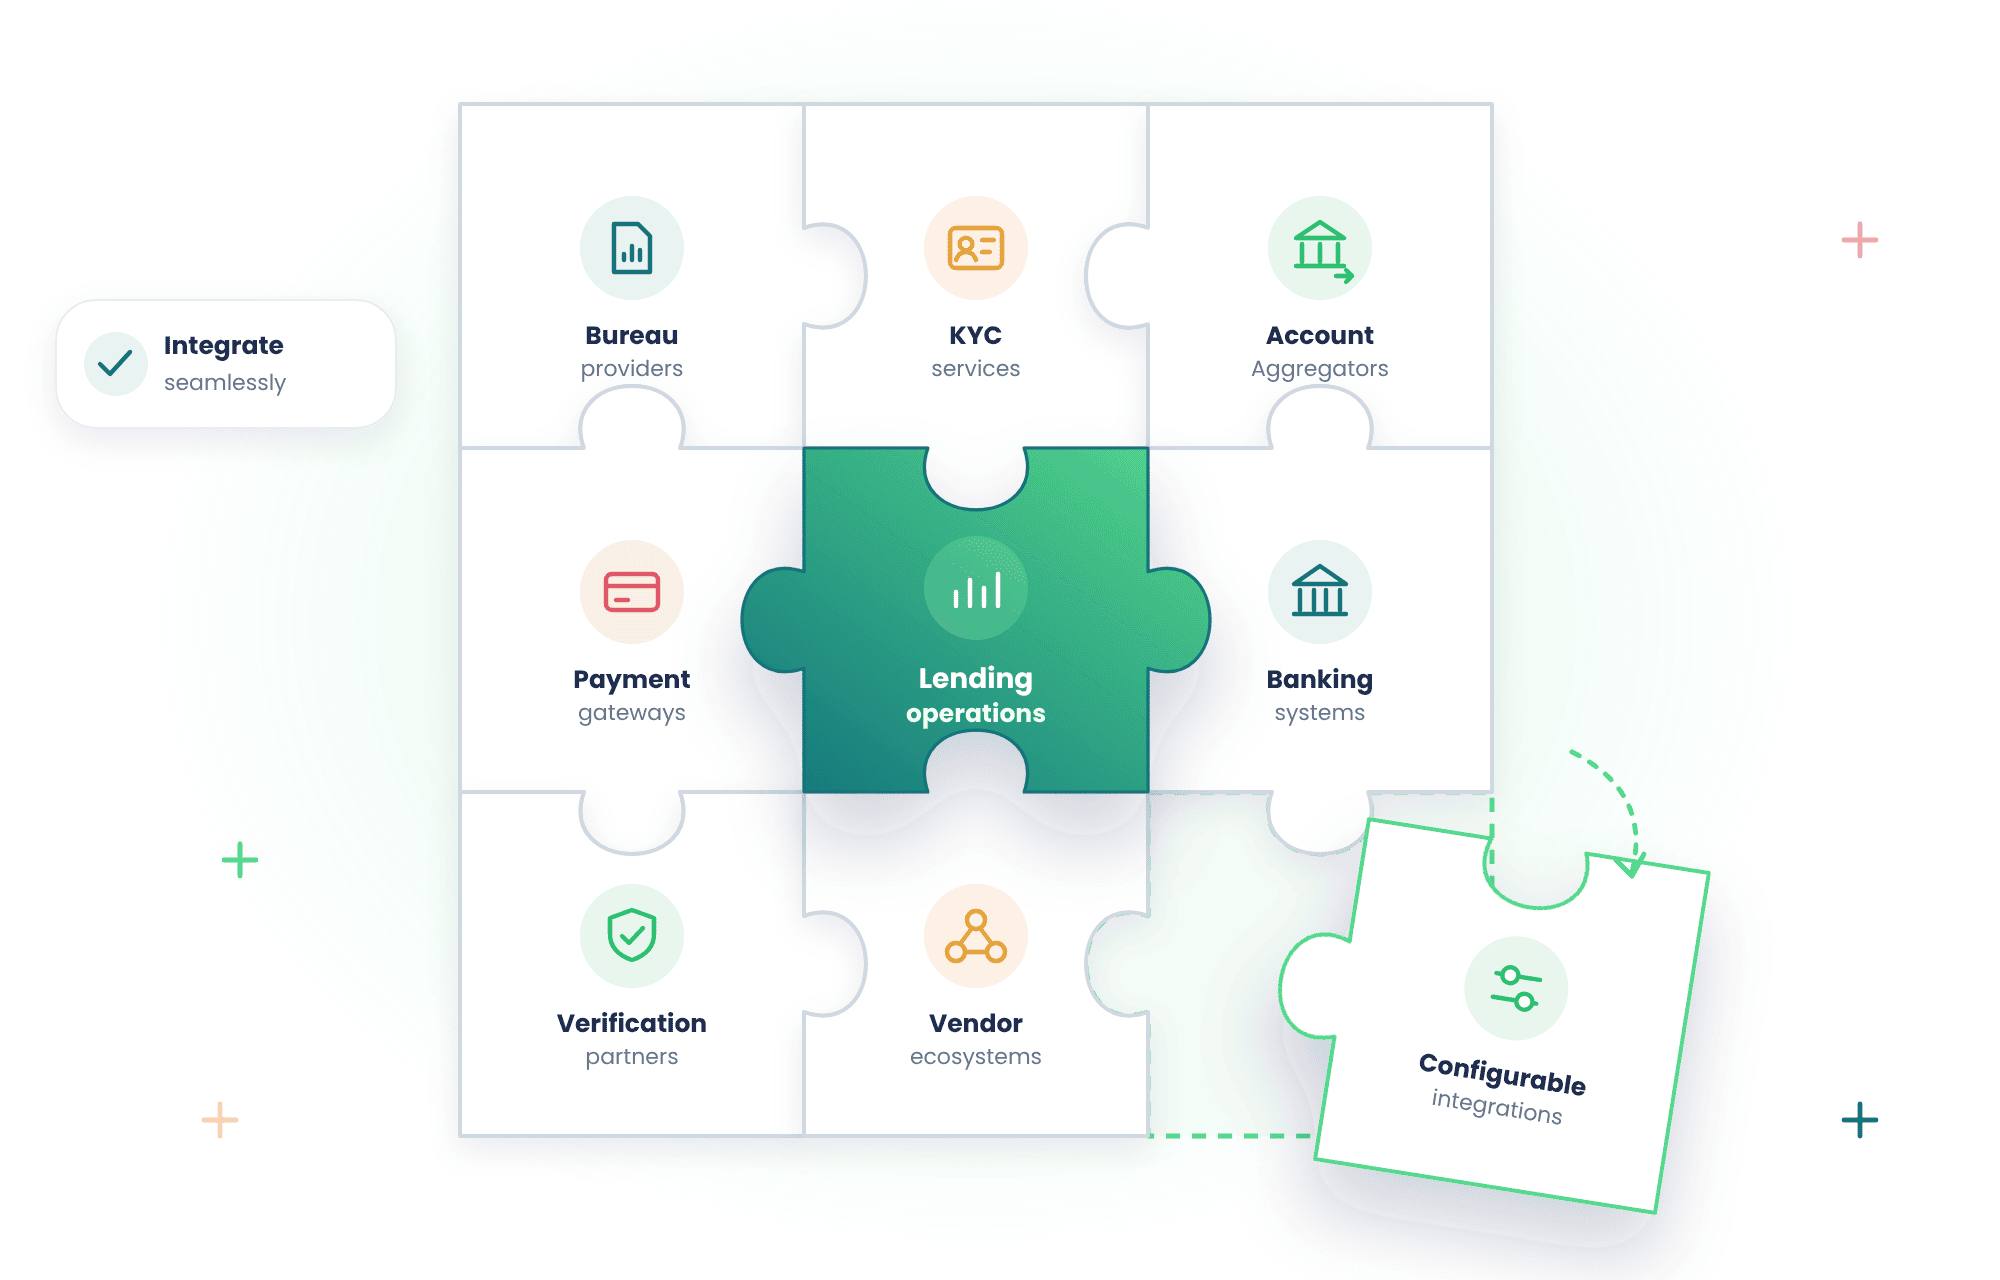 WHY CHOOSE FINTLY
Comparison of traditional lending process versus Fintly LOS
A Loan Origination System is software that manages the lending journey from lead generation and application processing through underwriting, approvals and disbursement. It helps lenders improve efficiency, consistency, and operational visibility.
Fintly LOS automates application intake, document management, underwriting workflows, approvals and disbursement readiness activities. This reduces manual effort and helps teams process applications more efficiently.
Yes. The platform includes automated underwriting capabilities that combine policy rules, risk assessments, financial analysis and approval workflows to support consistent lending decisions.
Yes. LOS includes configurable workflows that can support SME lending journeys, financial assessments, underwriting reviews, and approval processes.
Yes. Fintly LOS includes vendor management capabilities for coordinating verification partners, assigning cases, tracking SLAs and managing structured review workflows.
The platform includes configurable product management capabilities that allow lenders to update products, workflows, rules, and eligibility requirements through administrative controls.
Singpass Myinfo, Myinfo business and Corppass connectivity are on the Fintly Singapore roadmap. Until then, LOS supports document-based onboarding through Fintly IDP. Connection to these government services requires the institution's own onboarding with GovTech, and integrations depend on implementation requirements and approved connectivity arrangements.
LOS includes audit trails, role-based permissions, workflow controls, approval hierarchies and decision tracking capabilities that help institutions maintain visibility throughout the origination lifecycle.
Yes. LOS includes AI agents that prepare Income, Bureau and Banking Analysis and a draft credit memo, and Agentic PD for structured borrower discussions. Final credit decisions remain with authorised users.
Whether you're looking for loan origination software, an automated underwriting system, a vendor management system or a complete lending origination platform, Fintly LOS helps institutions streamline operations, improve decision-making and scale lending efficiently through a single configurable solution.
